
PHOT-410 · Lesson 10 of 12 · 28 min
Equipment, insurance and risk
Photography is equipment-intensive and risky in ways many small businesses are not. Cameras are dropped, stolen and made obsolete; memory cards fail; clients trip over light stands; a wedding cannot be reshot. Running a sound business means buying equipment wisely, accounting for it correctly, insuring against losses you cannot absorb, protecting data, and planning for what happens if you are injured or ill. This lesson covers equipment strategy, depreciation and capital cost allowance, the main types of insurance for photographers, data backup, a simple approach to risk assessment, and personal protection through health and disability coverage. It is general information; consult an accountant about tax treatment and a broker about insurance.
Equipment strategy
Equipment should serve revenue. Before buying, ask what jobs the item enables or improves, how often you will use it, and whether renting would be cheaper. A lens used twice a year for architectural jobs may be better rented and billed to those clients as an expense; a camera body used every week is worth owning. Professionals also need redundancy: a second body, spare batteries and cards, and backup lighting, because failure on a job is not an option.
Track equipment in an inventory with purchase date, cost, serial number and condition. The inventory supports insurance claims, depreciation records and planning for replacement. A simple replacement plan estimates the useful life of each item and sets aside money each year, which is the equipment replacement allowance used in the CODB calculation in Lesson 3.
Worked problem
Buy or rent
A tilt-shift lens costs $2,600 to buy and is expected to last 6 years, with a resale value of $800 at the end. Renting costs $90 per day. You expect to use it 8 days a year. Which is cheaper over 6 years, ignoring interest and tax?
Show solution
- Net cost of buying: \( 2600 - 800 = \$1800 \) over 6 years, or \( 1800 / 6 = \$300 \) a year.
- Cost of renting: \( 8 \times 90 = \$720 \) a year.
- Break-even use: \( 300 / 90 \approx 3.3 \) days a year.
Answer: Buying costs about $300 a year against $720 for renting, so buying is cheaper at 8 days a year. Renting would be cheaper only below about 3 days of use a year, though rental costs can often be billed to clients.
Depreciation and capital cost allowance
Equipment that lasts more than a year is a capital asset. Its cost is generally not deducted all at once but spread over its useful life through depreciation, although tax rules in both countries offer faster write-offs in some cases.
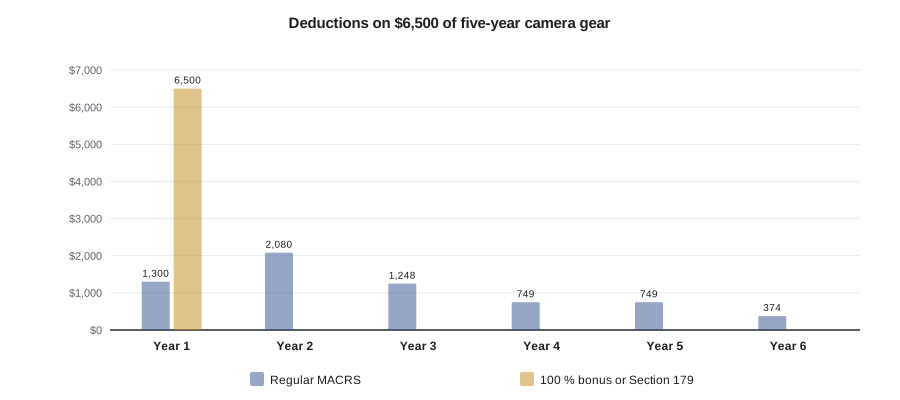
In the United States, equipment is depreciated under the Modified Accelerated Cost Recovery System (MACRS). Cameras, lenses, lighting and computers are generally five-year property, depreciated over six tax years with a half-year convention. Two faster options are common. Section 179 lets a business deduct the full cost of qualifying equipment in the year it is placed in service, up to $2,560,000 for 2026 with a phase-out above about $4.09 million of purchases, but not more than business taxable income. Bonus depreciation, which the 2025 tax law made permanent at 100% for qualifying property acquired after January 19, 2025, allows the full cost to be deducted in the first year and can create a loss. The de minimis safe harbor lets businesses deduct items costing $2,500 or less per item or invoice immediately, if they elect it. Selling equipment can trigger depreciation recapture taxed as ordinary income.
Worked problem
First-year write-off for new equipment
A photographer buys a camera body and lens for $6,500 and a computer for $3,000 in 2026, all five-year MACRS property. What can she deduct in year 1 using bonus depreciation, and what would year 1 be using regular MACRS (20% in year 1 under the half-year convention)?
Show solution
- Bonus depreciation at 100%: \( 6500 + 3000 = \$9500 \) deducted in year 1.
- Regular MACRS year 1: \( 9500 \times 0.20 = \$1900 \); later years take the rest on the MACRS schedule.
- Section 179 would also allow $9,500 in year 1, limited to her business income; bonus depreciation has no income limit.
Answer: $9,500 in year 1 with bonus depreciation or Section 179, against $1,900 under regular MACRS. Faster write-offs reduce tax sooner but do not change the total deducted over time, and selling later can trigger recapture.
Insurance for photographers
Insurance transfers the cost of losses you cannot easily absorb to an insurer in return for a premium. Photographers typically consider several types of coverage.
- Equipment coverage: protects cameras, lenses, computers and other gear against theft, loss and accidental damage, at home, in the studio, in vehicles and on location. Check whether coverage applies worldwide, whether it pays replacement cost or actual cash value, and the deductible. A homeowner's or tenant's policy usually excludes or limits business equipment.
- General liability: covers claims for bodily injury or property damage to others, such as a guest tripping over a light stand or a strobe scorching a venue's wall. Venues and clients often require proof of liability coverage, commonly $1 million to $2 million or more, and may ask to be named as additional insureds.
- Professional liability or errors and omissions (E&O): covers claims that your professional service caused financial loss, such as missing key wedding moments, losing images or infringing someone's rights by mistake.
- Data and cyber coverage: covers costs of data breaches, ransomware and recovery of client data.
- Business interruption: replaces income if a covered event, such as a studio fire, stops you working.
- Vehicle coverage: personal auto policies may not cover business use; tell your insurer if you drive to jobs.
- Drone coverage: aircraft liability insurance is a separate policy, and drone operations have their own rules; PHOT-350 covers aerial work.
Professional associations often offer group insurance programs designed for photographers. Compare these with policies from brokers, read the exclusions and keep certificates of insurance ready to send to venues.
Weighing premiums against risk
Expected loss is the probability of a loss multiplied by its cost. Comparing expected loss with the premium helps decide what to insure, but it is not the whole story: insurance is most valuable for rare, severe losses that would ruin the business, even when the premium exceeds the expected loss.
Worked problem
Is equipment insurance worth it?
Your gear is worth $15,000. You estimate a 5% chance per year of theft or serious damage. An equipment policy costs $450 a year with a $500 deductible. A liability claim from an injured guest might cost $250,000 but has an estimated probability of 0.2% a year, and liability coverage costs $350 a year. Compare expected losses with premiums.
Show solution
- Equipment expected loss: \( 0.05 \times 15\,000 = \$750 \); with insurance you bear only the deductible in a loss year, an expected \( 0.05 \times 500 = \$25 \).
- Equipment: premium $450 against an expected uninsured loss of $750, so insurance is good value.
- Liability expected loss: \( 0.002 \times 250\,000 = \$500 \) against a premium of $350.
- More important, a $250,000 claim would likely end the business, so the coverage protects against ruin.
Answer: Both policies are worthwhile. The equipment policy costs less than the expected loss, and liability coverage protects against a rare but catastrophic claim that you could not pay yourself.
Risk assessment
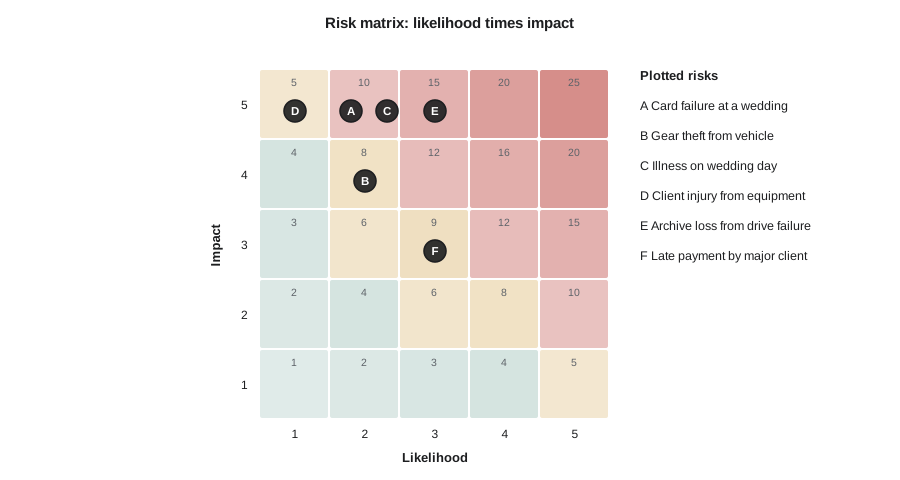
A simple risk matrix rates each risk by likelihood and impact, usually on a scale of 1 to 5, and multiplies them to give a score. High scores need action: avoid the risk, reduce it, transfer it through insurance or contracts, or accept it consciously.
| Risk | Likelihood (1 to 5) | Impact (1 to 5) | Score | Response |
|---|---|---|---|---|
| Memory card failure during a wedding | 2 | 5 | 10 | Dual card slots, second shooter, card rotation |
| Equipment theft from vehicle | 2 | 4 | 8 | Never leave gear visible, equipment insurance |
| Photographer illness on wedding day | 2 | 5 | 10 | Replacement network, contract clause |
| Client injury from equipment | 1 | 5 | 5 | Sandbags, cable management, liability insurance |
| Loss of archive from drive failure | 3 | 5 | 15 | 3-2-1 backup, offsite and cloud copies |
| Late payment by major client | 3 | 3 | 9 | Deposits, payment terms, reserve |
Data backup
Images are the product, and losing them can mean losing clients, reputation and sometimes a lawsuit. The widely used 3-2-1 rule calls for three copies of your data, on two different types of media, with one copy offsite. On location, cameras with dual card slots record simultaneously to two cards. After a shoot, copy the cards to a working drive and a backup drive before formatting, and sync to cloud storage. Test restores occasionally, since a backup you cannot restore is not a backup. Set a retention policy stating how long you keep client files, and tell clients in your contract.
Personal protection
For a sole photographer, the most valuable asset is the photographer. Illness or injury that prevents shooting stops income.
In the United States, self-employed photographers must arrange their own health insurance, often through the Health Insurance Marketplace or a professional association, and may be able to deduct premiums as self-employed health insurance. Disability insurance that replaces income if you cannot work, and a health savings account paired with a high-deductible plan, are also worth considering.
Build an emergency fund of three to six months of personal and business expenses, which protects against slow seasons as well as illness.
Safety on set
Risk management also means keeping people safe. Weigh down light stands with sandbags, tape or route cables away from walkways, keep fire exits clear, check the load limits of any rigging, and brief assistants and models on hazards such as hot lights, water near electrical equipment or uneven ground on location. On larger commercial shoots, a producer may prepare a written safety plan and confirm that the location's insurance and permits are in place. Shooting near roads, at heights, on water or with animals or minors calls for extra planning and sometimes specialist help. Documenting your safety steps shows care and can help if a claim arises.
Reviewing insurance each year
Insurance needs change as the business grows. Review your policies each year with your broker: update the equipment schedule with new purchases and remove sold items, check that liability limits still meet the requirements of your venues and clients, confirm coverage for any new activities such as video, drones or workshops, and compare premiums with alternatives. Keep copies of policies, certificates and the equipment inventory in cloud storage so you can file a claim quickly after a theft or fire.
Common mistakes
MistakeBuying equipment because it is new rather than because it earns money
InsteadTie purchases to jobs and compare buying with renting.
MistakeAssuming home insurance covers business gear
InsteadGet equipment coverage designed for professional use.
MistakeSkipping liability coverage because claims seem unlikely
InsteadInsure against rare but catastrophic claims.
MistakeKeeping only one copy of client images
InsteadFollow the 3-2-1 backup rule and test restores.
MistakeIgnoring income protection
InsteadConsider disability insurance and keep an emergency fund.
Summary and key terms
- Equipment purchases should be justified by revenue, with redundancy for critical items.
- Capital assets are deducted over time through CCA or MACRS, with faster options in some cases.
- Key insurance types are equipment, general liability, professional liability, cyber, business interruption, vehicle and drone coverage.
- Expected loss compares probability times cost with premiums; insurance matters most for catastrophic risks.
- A risk matrix ranks risks by likelihood and impact to guide responses.
- The 3-2-1 backup rule protects images: three copies, two media, one offsite.
- Health, disability coverage and an emergency fund protect the photographer.
- Capital asset
- Property that lasts more than a year, such as a camera.
- Capital cost allowance (CCA)
- Canada's tax depreciation system using asset classes.
- Half-year rule
- A rule limiting first-year CCA to half the normal amount.
- MACRS
- The US system for depreciating business property.
- Section 179
- A US election to deduct qualifying equipment in the year placed in service.
- Bonus depreciation
- A US first-year deduction of a percentage of an asset's cost.
- Recapture
- Income that arises when an asset sells for more than its remaining tax value.
- General liability insurance
- Coverage for injury or damage to others.
- Errors and omissions (E&O)
- Professional liability coverage for mistakes in services.
- 3-2-1 backup
- Three copies on two media with one offsite.
Practice problems
Work each problem on paper first, then reveal the answer to check.
A $4,000 camera is in Class 8 at 20%. What is first-year CCA under the half-year rule?
Show answer
\( 4000 \times 0.20 \times 0.5 = \$400 \).
What is second-year CCA on that camera?
Show answer
\( (4000 - 400) \times 0.20 = \$720 \).
A lens costs $1,800, resells for $600 after 4 years and rents at $75 a day. What is the break-even rental use per year?
Show answer
\( (1800 - 600) / 4 = 300 \); \( 300 / 75 = 4 \) days.
Expected loss with a 10% probability and $8,000 cost?
Show answer
\( 0.10 \times 8000 = \$800 \).
Name four types of insurance for photographers.
Show answer
Equipment, general liability, E&O, cyber, business interruption, vehicle, drone.
State the 3-2-1 backup rule.
Show answer
Three copies, two types of media, one offsite.
A risk has likelihood 4 and impact 3. What is its score?
Show answer
12.
Under US regular MACRS, what is year 1 depreciation on $5,000 of five-year property at 20%?
Show answer
\( \$1000 \).
Why insure against risks with low probability?
Show answer
Because rare catastrophic losses could end the business.
How large should an emergency fund be?
Show answer
Three to six months of personal and business expenses.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.