
ACCT-460 · Lesson 8 of 12 · 27 min
Planning and conducting an investigation
The first seven lessons described what frauds look like. The next three describe how forensic accountants investigate them. An investigation is a structured search for facts, carried out under legal, ethical and practical constraints, that must produce findings able to withstand challenge. Poorly planned investigations fail in predictable ways: evidence is lost or contaminated, the subject is alerted too early, the scope drifts, privacy or employment law is breached, privilege is waived, and the final report rests on assumptions rather than proof. This lesson follows the planning and early conduct of the Saltmarsh Industrial Supply Inc. investigation from the hotline reports to the first interviews.
Predication: why investigate at all?
Investigations should begin only when there is predication: the totality of circumstances that would lead a reasonable, professionally trained and prudent person to believe that a fraud has occurred, is occurring or will occur. Predication protects employees from fishing expeditions and protects the organization from claims of unfair treatment, and it defines the starting scope. It does not require proof; a credible tip, an anomaly found by analytics, an audit finding or a complaint from a customer can each supply it. In the Saltmarsh Industrial Supply Inc. matter, the two hotline reports, one specific and from an identified employee, the other anonymous but consistent with data the company held, gave predication for two lines of inquiry.
Triage of reports
Organizations with hotlines receive many reports, and most are not about fraud: workplace disputes, policy questions and grievances are common, and some fraud reports are vague or malicious. A triage process decides who looks at each report first, how quickly and with what independence. Reports implicating senior management or the finance function, or alleging financial statement fraud, should go to the audit committee rather than to management. Reports should be acknowledged, logged and tracked to resolution, and reporters, including anonymous reporters who can be contacted through the hotline system, should be told the outcome in general terms. The program below shows a simple triage of five reports received by Saltmarsh Industrial Supply Inc.'s audit committee chair in February 2026.
# Triage of hotline reports received by Saltmarsh's audit committee chair (invented data).
# Scores reflect specificity, potential size, who is implicated and whether evidence is offered;
# the triage decides who looks at a report first, not whether it is true.
reports = [
    {"id": "H-26-004", "summary": "Q4 shipments to two distributors were sent with side letters allowing returns",
     "specific": 3, "amount": 3, "senior": 3, "evidence": 2, "anonymous": False},
    {"id": "H-26-005", "summary": "Supervisor takes long lunches",
     "specific": 1, "amount": 0, "senior": 0, "evidence": 0, "anonymous": True},
    {"id": "H-26-006", "summary": "New logistics vendor invoices never match a delivery I can find",
     "specific": 2, "amount": 2, "senior": 1, "evidence": 1, "anonymous": True},
    {"id": "H-26-007", "summary": "Coworker expensed the same client dinner twice",
     "specific": 3, "amount": 1, "senior": 0, "evidence": 2, "anonymous": False},
    {"id": "H-26-008", "summary": "Talk that purchasing accepts gifts from a supplier",
     "specific": 1, "amount": 1, "senior": 1, "evidence": 0, "anonymous": True},
]
W = {"specific": 2, "amount": 3, "senior": 3, "evidence": 2}
def route(score, r):
    if r["senior"] >= 3 or score >= 20: return "audit committee with outside counsel"
    if score >= 10: return "internal audit investigation"
    if score >= 5: return "management review"
    return "log, acknowledge and monitor"
for r in sorted(reports, key=lambda r: -sum(W[k] * r[k] for k in W)):
    s = sum(W[k] * r[k] for k in W)
    print(f"{r['id']}  score {s:>2}  {route(s, r):<38} {'(anonymous)' if r['anonymous'] else ''}")
print(f" {r['summary']}")H-26-004 score 28 audit committee with outside counsel
Q4 shipments to two distributors were sent with side letters allowing returns
H-26-006 score 15 internal audit investigation (anonymous)
New logistics vendor invoices never match a delivery I can find
H-26-007 score 13 internal audit investigation
Coworker expensed the same client dinner twice
H-26-008 score 8 management review (anonymous)
Talk that purchasing accepts gifts from a supplier
H-26-005 score 2 log, acknowledge and monitor (anonymous)
Supervisor takes long lunchesThe revenue report, H-26-004, implicates a senior executive and scores highest, so it goes to the audit committee with outside counsel. The logistics invoice report, H-26-006, scores 15 and would normally go to internal audit, but Saltmarsh Industrial Supply Inc. has only a small internal audit function that reports to the chief financial officer, and the subject is in finance; the audit committee therefore adds it to the scope of the external investigation. This override shows why triage rules guide judgment but do not replace it. The duplicate dinner claim goes to internal audit and turns out to involve C. Varga, as lesson 4 described. The gift allegation is reviewed by management with a request for specifics, and the complaint about long lunches is logged and referred to human resources.
The investigation cycle and the fraud theory approach
Investigators commonly work through a cycle: understand the allegation and the environment, form hypotheses, plan how to test them, gather evidence, analyze it, refine or reject the hypotheses, and repeat until the questions are answered or the evidence runs out. The ACFE calls this the fraud theory approach. Investigators assume, for planning purposes, the worst-case version of what might have happened, design tests that would prove or disprove it, and revise the theory as evidence arrives. A theory that the evidence contradicts is abandoned, not defended.
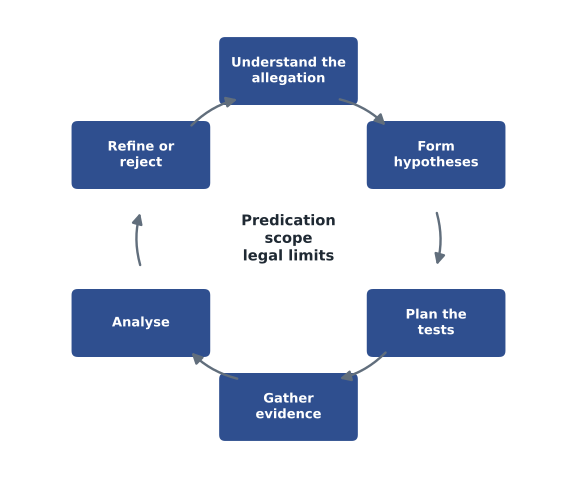
For the vendor allegation, the initial theory is that an employee with access to the vendor master and to invoice approval created a shell vendor and caused it to be paid for services never provided. Tests that would support it include evidence of who created the vendor, whether services were received, links between the vendor and an employee, and the flow of funds. Tests that would refute it include evidence of real logistics services, such as delivery records, carrier documents and the business units' confirmation that they used the vendor. For the revenue allegation, the theory is that year-end shipments were made on terms that made them reversible, that those terms were concealed, and that someone benefited. The team plans tests for each element.
Scope, team and budget
The engagement letter from lesson 1 sets the initial scope: the two allegations and related matters found in the course of the work. Defining scope precisely matters, because investigations naturally expand as new leads appear, and each expansion costs time, money and disruption. The team agrees with counsel a process for deciding whether new matters are added. At Saltmarsh Industrial Supply Inc., the vendor review led to the scoring of all vendors (lesson 5) and the card and expense tests (lesson 4), which counsel approved as related matters; a separate concern about a former employee's non-competition agreement was referred back to the company.
The team is chosen for the matter. For Saltmarsh Industrial Supply Inc., Corbett Lane Forensic LLP assigns a partner, a senior forensic accountant for each workstream, a data analyst, and a digital forensics specialist, with an employment lawyer on counsel's side. Budgets for investigations are estimates, because the work depends on what is found; the firm gives counsel a phased budget, with decision points after the data analysis and after the first interviews.
Legal and practical constraints
Investigations must respect the law, the organization's policies and the rights of the people involved. Employment law governs what an employer may require of employees, such as cooperation with an investigation, and how it may discipline them; unionized workplaces have collective agreements that may give employees the right to representation in interviews. Privacy law governs what personal information may be collected, used and disclosed, discussed further in lesson 9. Policies on the use of company devices and email determine whether the organization may search them; investigators should confirm that the organization's policy permits the search and that it is proportionate. Privilege, discussed in lesson 1, must be protected by routing communications through counsel and labeling documents appropriately.
In the United States, employers generally have broad rights to search company-owned systems under their policies, subject to state privacy laws, the federal Stored Communications Act for some accounts, the National Labor Relations Act's protection of concerted activity, and collective agreements, which may give unionized employees the right to representation in investigatory interviews.
Insurance matters too. A commercial crime or fidelity policy usually requires the insured to give notice soon after discovering a loss and to file a proof of loss within a set period, and it may require cooperation with the insurer's investigation. Missing these deadlines can void coverage. Saltmarsh Industrial Supply Inc.'s counsel notifies Harrow Mutual Insurance on March 2, 2026, within days of the preliminary findings on Northfield.
Preserving evidence
As soon as an investigation is likely, the organization must preserve relevant evidence. Counsel issues a legal hold instructing custodians not to delete documents and suspending automatic deletion of email and other records. Electronic evidence is collected in a forensically sound way, creating verified copies (images) of hard drives, phones and mailboxes with documented chain of custody, so that its integrity can be proved later; CISSP-116 discusses digital evidence handling. Paper records are secured, copied and logged. Accounting system data are extracted with control totals that reconcile to the ledger, as ACCT-341 described.
Preservation often has to happen quietly. At Saltmarsh Industrial Supply Inc., the digital forensics specialist images R. Calloway's laptop and mailbox on March 10, 2026 under the company's device policy, at a time arranged with IT so that no one is alerted. The vendor master change log, invoice images and payment records are extracted the same day. The revenue workstream preserves the email accounts and phones of the sales team before anyone is interviewed.
Sequencing the work
Investigators usually work from the outside in. They examine documents and data first, then interview neutral witnesses who can explain processes, then corroborating witnesses, then possible co-conspirators, and finally the subject. This order lets each interview build on what is already known, lets the investigator test the subject's explanations against evidence, and reduces the chance that the subject learns of the investigation early and destroys evidence or coordinates stories. The subject is usually interviewed last, but before the organization takes disciplinary action, so that the subject has a fair opportunity to explain.
The Saltmarsh Industrial Supply Inc. plan follows this sequence. The data analysis in lessons 3 to 5 runs in late February. Interviews of payables clerks about how vendors are added and invoices approved, of warehouse staff about Northfield deliveries, and of the controller about approval limits take place in early March. R. Calloway is interviewed on March 12, 2026; immediately afterwards, the company places him on paid leave and suspends his system access, a decision taken by the company on employment counsel's advice, not by the investigators. G. Pellerin, the director of Northfield, agrees to be interviewed on March 19. The revenue workstream follows a similar path, interviewing the warehouse staff and the controller before the distributors and finally C. Varga.
Documenting and reporting progress
Every step of the investigation is documented in working papers that record what was done, by whom, when, on what evidence and with what result. Documentation should be factual and neutral, because it may be produced in litigation. Interim reporting to counsel is usually oral or in brief memoranda, to limit the number of documents that could be disclosed and to allow the scope to be adjusted. The final report, discussed in lesson 12, comes only when the work is complete.
Worked problem
Deciding the order of interviews
An investigation concerns suspected kickbacks paid by a supplier to a purchasing manager. Potential interviewees are the purchasing manager, two buyers who report to the manager, the accounts payable clerk who processes the supplier's invoices, the supplier's sales representative and the warehouse supervisor. In what order should they be interviewed?
Show solution
- Start with neutral process witnesses: the payables clerk and the warehouse supervisor, who can explain how invoices and deliveries are handled.
- Next, the two buyers, who may corroborate how orders were directed to the supplier and may know of gifts or meetings.
- Then the supplier's representative, if counsel agrees, recognizing the risk that the supplier will alert the manager.
- Finally the purchasing manager, after the documents and other interviews have established what needs explaining.
Answer: Work from the outside in: process witnesses, then corroborating witnesses, then the possible co-conspirator, and the subject last.
Common mistakes
MistakeStarting an investigation on rumor alone.
InsteadEstablish predication: circumstances that would lead a prudent professional to believe fraud may have occurred.
MistakeLetting management investigate a report that implicates the finance function.
InsteadRoute such reports to the audit committee and independent investigators.
MistakeInterviewing the subject first to save time.
InsteadWork from documents and neutral witnesses inward, interviewing the subject last but before discipline.
MistakeImaging devices without checking policy and law.
InsteadConfirm that policy and law permit the search and that it is proportionate.
MistakeMissing the insurer's notice deadline.
InsteadNotify the insurer promptly and diary the proof-of-loss deadline.
MistakeLetting the scope grow without decisions.
InsteadAgree a process with counsel for adding related matters and referring others.
Summary and key terms
- Investigations need predication, a reasonable basis to believe fraud may have occurred.
- Triage routes reports by seriousness, independence and seniority of the people implicated; judgment can override scores.
- The fraud theory approach forms worst-case hypotheses, tests them and revises or abandons them.
- Scope, team and phased budgets are agreed with counsel, with a process for related matters.
- Employment law, privacy law, device policies, privilege and insurance conditions constrain the work.
- Evidence is preserved early through legal holds and forensically sound collection, often quietly.
- Work proceeds from documents and neutral witnesses inward, with the subject interviewed last.
- Predication
- The circumstances that would lead a reasonable professional to believe fraud has occurred, justifying an investigation.
- Triage
- Deciding who examines each report first, how quickly and with what independence.
- Fraud theory approach
- Forming a hypothesis of what happened, testing it and refining or abandoning it as evidence emerges.
- Legal hold
- An instruction to preserve documents and suspend deletion because of anticipated litigation or investigation.
- Forensic image
- A verified bit-for-bit copy of digital media collected with documented chain of custody.
- Chain of custody
- The record of who held evidence, when and what was done with it.
- Proof of loss
- The insured's formal statement of a loss to an insurer, usually due within a set period.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What is predication, and why does it matter?
Show answer
The circumstances that would lead a prudent professional to believe fraud has occurred; it justifies the investigation and protects employees from fishing expeditions.
In the triage program, why does H-26-004 go to the audit committee?
Show answer
It implicates a senior executive, which triggers that route regardless of score.
Why did the audit committee override the triage route for H-26-006?
Show answer
Internal audit reports to the CFO and the subject is in finance, so independence required an external investigation.
Change the 'senior' rating of H-26-007 to 3 and rerun. Where does it go?
Show answer
To the audit committee with outside counsel.
Describe the fraud theory approach in three steps.
Show answer
Form a worst-case hypothesis, design and perform tests to prove or disprove it, and refine or abandon it as evidence emerges.
Why is evidence preserved quietly at the start?
Show answer
To prevent the subject or others from destroying or altering it once alerted.
Why is the subject usually interviewed last but before discipline?
Show answer
So the interview can test explanations against evidence, and the subject has a fair chance to respond before action.
Who decided to place Calloway on leave, and why does that matter?
Show answer
The company, on employment counsel's advice; investigators gather facts and do not make employment decisions.
Why must the insurer be notified promptly?
Show answer
Crime policies require timely notice and proof of loss; missing deadlines can void coverage.
Name three legal constraints on an investigation.
Show answer
Employment law and collective agreements, privacy law, device and email policies, privilege rules, insurance conditions.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.