
ACCT-499 · Lesson 8 of 12 · 27 min
Tax and finance: the effective tax rate, capital structure and valuation
Jonah's workstream covers two questions that boards ask about every company: is the tax position reasonable and well managed, and is the company financed sensibly for its plans? The capstone does not prepare tax returns or value the company for a transaction; both are outside scope. But a team that ignored tax and financing would miss important parts of Bluestem's story, including how its reporting issues would affect its loan covenants. ACCT-351 and ACCT-352 taught tax, and FIN-201 and FIN-301 taught corporate finance. This lesson applies them at the level of an advisory review.
Reading the tax note
Under IAS 12, Bluestem's tax note reconciles the tax expense in the income statement to the tax that would result from applying the statutory rate to profit before tax. The reconciliation is the best single summary of a company's tax profile: it shows the permanent differences, credits, rate differences and changes in unrecognized deferred tax assets that make the effective rate differ from the statutory one. Bluestem's combined Canadian statutory rate is 29 per cent (15 per cent federal plus 14 per cent Nova Scotia). The program reproduces the 2026 reconciliation from the tax note.
# Bluestem Water Instruments Inc. (invented), in thousands of dollars, years ended December 31.
YEARS = [2024, 2025, 2026]
IS = {'Hardware revenue': [138000, 149500, 161200], 'Subscription revenue': [44000, 55600, 69800],
      'Hardware cost of sales': [82800, 92700, 104800], 'Subscription cost of sales': [11000, 13300, 16100],
      'Selling, general and admin': [42000, 48500, 56900], 'Research and development': [18200, 21000, 23600],
      'Depreciation': [6200, 6900, 7600], 'Amortization of intangibles': [3000, 4800, 4800],
      'Interest expense': [2100, 3900, 4600], 'Income tax expense': [3300, 2500, 2500]}
BS = {  # balances at December 31, 2023 to 2026
      'Cash': [18000, 24200, 25500, 23400], 'Receivables': [26000, 30000, 39800, 52100],
      'Inventories': [22000, 26000, 31500, 41900], 'Other current assets': [2800, 3000, 3600, 4100],
      'Property, plant and equipment': [45000, 48000, 51000, 53500], 'Right-of-use assets': [13000, 12000, 15500, 14800],
      'Intangible assets': [9000, 6000, 19200, 14400], 'Goodwill': [8000, 8000, 24000, 24000],
      'Payables': [15000, 17000, 19500, 22700], 'Accrued liabilities': [8000, 9000, 10500, 11200],
      'Deferred revenue': [11000, 14000, 18500, 21000], 'Warranty provision': [2300, 2500, 2700, 2600],
      'Income taxes payable': [1200, 1300, 900, 700], 'Lease liabilities': [13500, 13000, 16800, 16300],
      'Borrowings': [28000, 25000, 57000, 60000], 'Deferred tax liabilities': [1800, 2000, 2300, 2700],
      'Share capital': [40000, 40000, 40000, 42000], 'Retained earnings': [23000, 33400, 41900, 49000]}
CF = {'Cash from operations': [20900, 15900, 5800], 'Capital expenditure': [-8000, -8400, -8400],
      'Acquisition of Merrow Lane': [0, -34000, 0], 'Dividends paid': [-3000, -3000, -3000]}
def rev(i): return IS['Hardware revenue'][i] + IS['Subscription revenue'][i]
def cogs(i): return IS['Hardware cost of sales'][i] + IS['Subscription cost of sales'][i]
def ebit(i): return rev(i) - cogs(i) - sum(IS[k][i] for k in ('Selling, general and admin', 'Research and development', 'Depreciation', 'Amortization of intangibles'))
def ni(i): return ebit(i) - IS['Interest expense'][i] - IS['Income tax expense'][i]
ASSETS = ['Cash', 'Receivables', 'Inventories', 'Other current assets', 'Property, plant and equipment', 'Right-of-use assets', 'Intangible assets', 'Goodwill']
CUR_A = ASSETS[:4]
CUR_L = ['Payables', 'Accrued liabilities', 'Deferred revenue', 'Warranty provision', 'Income taxes payable']
LIABS = CUR_L + ['Lease liabilities', 'Borrowings', 'Deferred tax liabilities']
def tot(keys, t): return sum(BS[k][t] for k in keys)

# Lesson 8: effective tax rate reconciliation, 2026 (Canadian view; invented amounts in thousands).
pbt = ebit(2) - IS['Interest expense'][2]
items = [('Tax at the combined statutory rate of 29%', 0.29 * pbt),
         ('Non-deductible stock-based compensation and meals', 310),
         ('SR&ED investment tax credits recognized in tax expense', -880),
         ('Lower rates on US subsidiary income', -190),
         ('Change in unrecognized deferred tax assets (US losses)', -330),
         ('Prior-year adjustments', -64)]
total = sum(v for _, v in items)
print(f"Profit before tax: {pbt:,}")
for k, v in items: print(f"  {k:58} {v:>8,.0f}")
print(f"  {'Income tax expense':58} {total:>8,.0f}   (reported {IS['Income tax expense'][2]:,})")
print(f"Effective tax rate: {total / pbt:.1%} against a statutory rate of 29.0%")
print("\nIf the team's adjustments (pre-tax -8,650) were booked, with the impairment not deductible:")
adj_pbt = pbt - 8650
adj_tax = total - 0.29 * (1283 + 1700)
print(f" profit before tax {adj_pbt:,}, tax {adj_tax:,.0f}, effective rate {adj_tax / adj_pbt:.1%}")Profit before tax: 12,600 Tax at the combined statutory rate of 29% 3,654 Non-deductible stock-based compensation and meals 310 SR&ED investment tax credits recognized in tax expense -880 Lower rates on US subsidiary income -190 Change in unrecognized deferred tax assets (US losses) -330 Prior-year adjustments -64 Income tax expense 2,500 (reported 2,500) Effective tax rate: 19.8% against a statutory rate of 29.0% If the team's adjustments (pre-tax -8,650) were booked, with the impairment not deductible: profit before tax 3,950, tax 1,635, effective rate 41.4%
Bluestem's effective tax rate of 19.8 per cent is well below the 29 per cent statutory rate. The largest reconciling item is the credit for research and development: as a public corporation, Bluestem is not a Canadian-controlled private corporation, so its federal SR&ED investment tax credits are non-refundable and earned at the general rate of 15 per cent of qualifying expenditures, applied against tax payable. Nova Scotia also offers a provincial research credit. The credits recognized in tax expense reduce the effective rate by about seven points. Smaller items include non-deductible stock-based compensation and meals, lower tax on the US subsidiary's income, and the recognition of previously unrecognized US losses. The team checked that the SR&ED claims are supported by project documentation, because the CRA reviews claims closely and a reassessment would raise the effective rate. It found that the documentation for two projects was thin and recommends contemporaneous records of technological uncertainty and experimental work.
The second part of the output shows what would happen if Bluestem booked the team's adjustments from Lesson 5. The goodwill impairment is not deductible for tax, so profit falls more than tax expense and the effective rate jumps. This is a useful check on the team's own work: a reader of the adjusted figures would see an unusual effective rate and would need the explanation.
Deferred tax and uncertain positions
Bluestem's deferred tax liability of 2.7 million arises mainly from accelerated capital cost allowance on equipment and from the acquired Merrow Lane intangibles, whose tax base is lower than their carrying amount. If the Merrow Lane goodwill is impaired, there is no deferred tax effect, because IAS 12 prohibits recognizing deferred tax on the initial recognition of goodwill. The team also asked whether Bluestem has any uncertain tax positions under IFRIC 23. Management identified one: the transfer price charged by the Canadian parent to the US subsidiary for cloud services. It has a supporting study and has recognized no liability, which the team considers reasonable but recommends updating, because the subsidiary's role has grown since the study was done.
Global minimum tax rules do not apply to Bluestem. The OECD Pillar Two rules, enacted in Canada through the Global Minimum Tax Act and adopted in various forms elsewhere, apply to multinational groups with consolidated revenue of at least 750 million euros in two of the four preceding years. Bluestem's revenue is about a third of that threshold. The team notes it for completeness because a large acquisition could bring Bluestem closer.
Tax planning opportunities
The team identifies, at a high level, opportunities worth discussing with Bluestem's tax advisers. It does not provide tax advice, and every idea must be evaluated by qualified advisers against current law. Three opportunities stand out: improving research credit documentation to protect existing claims and support claims for software development at Merrow Lane; reviewing the transfer pricing study as the cross-border business grows; and considering government incentives for clean technology and water infrastructure, several of which apply to monitoring equipment. Each would need detailed work beyond the engagement.
Canadian programs worth checking include the clean technology investment tax credit, which applies to certain equipment used in clean technology, and provincial programs for innovation. Eligibility for any specific credit depends on details the team cannot verify, and rules change frequently, so the report lists them as questions for advisers rather than recommendations.
Capital structure and covenants
Bluestem financed the Merrow Lane acquisition with a term loan, raising borrowings from 25 to 57 million in 2025 and 60 million in 2026. Its credit agreement has two covenants, tested quarterly: net debt to EBITDA must not exceed 3.0 times, and interest coverage (EBIT divided by interest) must be at least 3.0 times. Covenant definitions are set in the agreement, not in accounting standards; Bluestem's agreement defines EBITDA before impairment charges and uses the reported financial statements.
| Covenant measure | As reported 2026 | After warranty and bill-and-hold adjustments | Limit |
|---|---|---|---|
| EBITDA (thousands) | 29,600 | 26,617 | n/a |
| Net debt (borrowings less cash) | 36,600 | 36,600 | n/a |
| Net debt / EBITDA | 1.24 times | 1.38 times | At most 3.0 times |
| EBIT (thousands) | 17,200 | 14,217 | n/a |
| Interest coverage | 3.74 times | 3.09 times | At least 3.0 times |
The leverage covenant has plenty of headroom. The interest coverage covenant does not. As reported, coverage is 3.74 times; if management booked the warranty and bill-and-hold adjustments, coverage would fall to about 3.09 times, barely above the limit. A further small decline in operating income, or a rise in interest rates on the floating-rate term loan, could cause a breach. This is one of the team's most important findings, because it connects accounting judgments to financing risk. Management needs to understand its covenant headroom under realistic accounting, and the board needs to know that the company's financing depends on the quality of its earnings.
The team recommends that Bluestem monitor covenant headroom monthly with forecasts, consider hedging part of its floating-rate exposure, and open an early conversation with its lender if the accounting changes are made. Lenders generally prefer early, transparent discussion to a surprise, and covenant amendments are routine when a company is fundamentally sound. Improving working capital, as Lesson 4 showed, would release cash to reduce debt and interest.
A valuation sketch
Valuing Bluestem is outside scope, but a rough valuation helps the board see how the team's recommendations would create value. The team uses the discounted cash flow approach from FIN-301: forecast free cash flows for five years, discount them at the weighted average cost of capital, add a terminal value and subtract net debt. The program builds the cost of capital from the capital asset pricing model with a small-company premium, then runs the valuation and a sensitivity table.
# Bluestem Water Instruments Inc. (invented), in thousands of dollars, years ended December 31.
YEARS = [2024, 2025, 2026]
IS = {'Hardware revenue': [138000, 149500, 161200], 'Subscription revenue': [44000, 55600, 69800],
      'Hardware cost of sales': [82800, 92700, 104800], 'Subscription cost of sales': [11000, 13300, 16100],
      'Selling, general and admin': [42000, 48500, 56900], 'Research and development': [18200, 21000, 23600],
      'Depreciation': [6200, 6900, 7600], 'Amortization of intangibles': [3000, 4800, 4800],
      'Interest expense': [2100, 3900, 4600], 'Income tax expense': [3300, 2500, 2500]}
BS = {  # balances at December 31, 2023 to 2026
      'Cash': [18000, 24200, 25500, 23400], 'Receivables': [26000, 30000, 39800, 52100],
      'Inventories': [22000, 26000, 31500, 41900], 'Other current assets': [2800, 3000, 3600, 4100],
      'Property, plant and equipment': [45000, 48000, 51000, 53500], 'Right-of-use assets': [13000, 12000, 15500, 14800],
      'Intangible assets': [9000, 6000, 19200, 14400], 'Goodwill': [8000, 8000, 24000, 24000],
      'Payables': [15000, 17000, 19500, 22700], 'Accrued liabilities': [8000, 9000, 10500, 11200],
      'Deferred revenue': [11000, 14000, 18500, 21000], 'Warranty provision': [2300, 2500, 2700, 2600],
      'Income taxes payable': [1200, 1300, 900, 700], 'Lease liabilities': [13500, 13000, 16800, 16300],
      'Borrowings': [28000, 25000, 57000, 60000], 'Deferred tax liabilities': [1800, 2000, 2300, 2700],
      'Share capital': [40000, 40000, 40000, 42000], 'Retained earnings': [23000, 33400, 41900, 49000]}
CF = {'Cash from operations': [20900, 15900, 5800], 'Capital expenditure': [-8000, -8400, -8400],
      'Acquisition of Merrow Lane': [0, -34000, 0], 'Dividends paid': [-3000, -3000, -3000]}
def rev(i): return IS['Hardware revenue'][i] + IS['Subscription revenue'][i]
def cogs(i): return IS['Hardware cost of sales'][i] + IS['Subscription cost of sales'][i]
def ebit(i): return rev(i) - cogs(i) - sum(IS[k][i] for k in ('Selling, general and admin', 'Research and development', 'Depreciation', 'Amortization of intangibles'))
def ni(i): return ebit(i) - IS['Interest expense'][i] - IS['Income tax expense'][i]
ASSETS = ['Cash', 'Receivables', 'Inventories', 'Other current assets', 'Property, plant and equipment', 'Right-of-use assets', 'Intangible assets', 'Goodwill']
CUR_A = ASSETS[:4]
CUR_L = ['Payables', 'Accrued liabilities', 'Deferred revenue', 'Warranty provision', 'Income taxes payable']
LIABS = CUR_L + ['Lease liabilities', 'Borrowings', 'Deferred tax liabilities']
def tot(keys, t): return sum(BS[k][t] for k in keys)

# Lesson 8: weighted average cost of capital and a five-year DCF valuation of Bluestem (illustrative inputs).
rf, erp, beta, size = 0.035, 0.055, 1.15, 0.010
ke = rf + beta * erp + size
kd, tax = 0.068, 0.26
E, D = 210000, BS['Borrowings'][3] + BS['Lease liabilities'][3]      # market value of equity (assumed) and debt
wacc = E / (E + D) * ke + D / (E + D) * kd * (1 - tax)
print(f"Cost of equity {ke:.2%}; after-tax cost of debt {kd * (1 - tax):.2%}; weights E {E / (E + D):.0%} D {D / (E + D):.0%}; WACC {wacc:.2%}")
rev0, margin0 = rev(2), ebit(2) / rev(2)
fcf, r = [], rev0
for y in range(1, 6):
    r *= 1.09 if y <= 2 else 1.06
    m = min(margin0 + 0.008 * y, 0.115)
    nopat = r * m * (1 - tax)
    reinvest = 0.30 * nopat
    fcf.append(nopat - reinvest)
def ev(w, g):
    pv = sum(f / (1 + w) ** (k + 1) for k, f in enumerate(fcf))
    return pv + fcf[-1] * (1 + g) / (w - g) / (1 + w) ** 5
g = 0.025
base = ev(wacc, g)
net_debt = D - BS['Cash'][3]
print("Free cash flow forecast: " + ", ".join(f"{f:,.0f}" for f in fcf))
print(f"Enterprise value {base:,.0f}; less net debt {net_debt:,} = equity value {base - net_debt:,.0f}")
print("\nSensitivity of equity value (rows WACC, columns terminal growth)")
print("        " + "".join(f"{gg:>10.1%}" for gg in (0.015, 0.025, 0.035)))
for w in (wacc - 0.01, wacc, wacc + 0.01):
print(f"{w:>7.2%} " + "".join(f"{ev(w, gg) - net_debt:>10,.0f}" for gg in (0.015, 0.025, 0.035)))Cost of equity 10.82%; after-tax cost of debt 5.03%; weights E 73% D 27%; WACC 9.28%
Free cash flow forecast: 10,755, 12,860, 14,837, 17,005, 19,380
Enterprise value 244,293; less net debt 52,900 = equity value 191,393
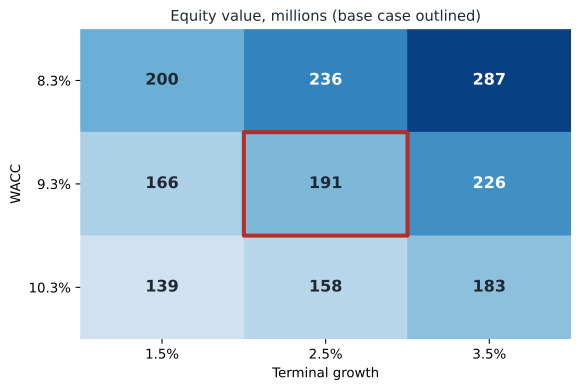
Sensitivity of equity value (rows WACC, columns terminal growth)
1.5% 2.5% 3.5%
8.28% 199,954 235,916 286,920
9.28% 165,640 191,393 226,056
10.28% 139,198 158,375 183,207The weighted average cost of capital comes to about 9.3 per cent, and the base-case equity value to about 191 million, close to the assumed market value of 210 million used in the weights. The sensitivity table makes the main point: a one-point change in the cost of capital or the terminal growth rate moves the equity value by 25 to 45 million. The forecast assumes margins recover by about 0.8 points a year to 11.5 per cent and that the company reinvests 30 per cent of after-tax operating profit. If working capital continued to absorb cash as it did in 2026, reinvestment would be higher and the value lower. The team uses the model to show the value of its recommendations, not to tell the board what the company is worth.
Worked problem
Testing covenant headroom
Bluestem's 2026 interest expense is 4.6 million and its floating-rate term loan of 55 million would cost an extra 550,000 dollars a year for each one-point rise in rates. With adjusted EBIT of 14.2 million, how far could rates rise before interest coverage falls below 3.0?
Show solution
- Maximum interest for coverage of 3.0 = 14.2 / 3.0 = about 4.73 million.
- Headroom = 4.73 - 4.60 = about 0.13 million.
- Rate rise that uses the headroom = 0.13 / 0.55 = about 0.24 points.
Answer: About a quarter of a percentage point, assuming EBIT does not change: very little headroom.
Common mistakes
MistakeTreating the effective tax rate as a single number to compare with peers.
InsteadRead the reconciliation to understand what drives the rate.
MistakeRecommending specific tax strategies without qualified advice.
InsteadList opportunities as questions for the company's tax advisers.
MistakeAssuming covenant measures follow accounting standards.
InsteadRead the credit agreement's definitions, such as EBITDA before impairment.
MistakeIgnoring how accounting adjustments affect covenants.
InsteadRecalculate covenant ratios under the proposed adjustments.
MistakePresenting a DCF value as the company's worth.
InsteadUse valuation to show the effect of recommendations, with sensitivity analysis.
Summary and key terms
- The tax reconciliation is the best summary of a company's tax profile.
- Bluestem's 19.8 per cent effective rate reflects mainly SR&ED credits against a 29 per cent statutory rate.
- Research credit documentation and the transfer pricing study need updating.
- Pillar Two does not apply at Bluestem's size.
- Interest coverage would fall to about 3.09 times against a 3.0 covenant if the adjustments were booked.
- A DCF sketch with sensitivity shows how recommendations affect value.
- SR&ED investment tax credit
- A federal credit for qualifying scientific research and experimental development expenditures.
- Effective tax rate
- Income tax expense divided by profit before tax.
- Tax rate reconciliation
- A disclosure reconciling tax at the statutory rate with reported tax expense.
- Covenant
- A condition in a loan agreement, often a financial ratio the borrower must maintain.
- Interest coverage
- EBIT divided by interest expense.
- Weighted average cost of capital (WACC)
- The blended required return of a company's debt and equity investors.
- Terminal value
- The value of cash flows beyond the explicit forecast period.
Practice problems
Work each problem on paper first, then reveal the answer to check.
What is Bluestem's 2026 effective tax rate, and what is the main reason it is below the statutory rate?
Show answer
19.8 per cent; SR&ED investment tax credits.
Why does the effective rate rise if the goodwill impairment is booked?
Show answer
The impairment reduces profit but is not deductible, so tax falls less than profit.
Why do Pillar Two rules not apply to Bluestem?
Show answer
Its revenue is well below the 750-million-euro threshold.
Calculate net debt to EBITDA as reported.
Show answer
36,600 / 29,600 = about 1.24 times.
Calculate interest coverage after the warranty and bill-and-hold adjustments.
Show answer
14,217 / 4,600 = about 3.09 times.
Why does the credit agreement exclude the impairment from EBITDA?
Show answer
Because the agreement defines EBITDA before impairment charges; covenant definitions are contractual.
What three actions does the team recommend on financing?
Show answer
Monitor covenant headroom monthly, consider hedging floating-rate debt, and talk to the lender early.
What is the base-case WACC in the valuation sketch?
Show answer
About 9.3 per cent.
How much does equity value change between the lowest and highest cells of the sensitivity table?
Show answer
From about 139 million to about 287 million.
Why does the team present tax opportunities as questions for advisers?
Show answer
It does not provide tax advice, eligibility depends on facts it cannot verify, and rules change often.
Lesson quiz · 5 questions
Score 60% or more to complete this lesson.
Create a free account to save your progress, take quizzes and earn a certificate.